← All case studiesIllustrative example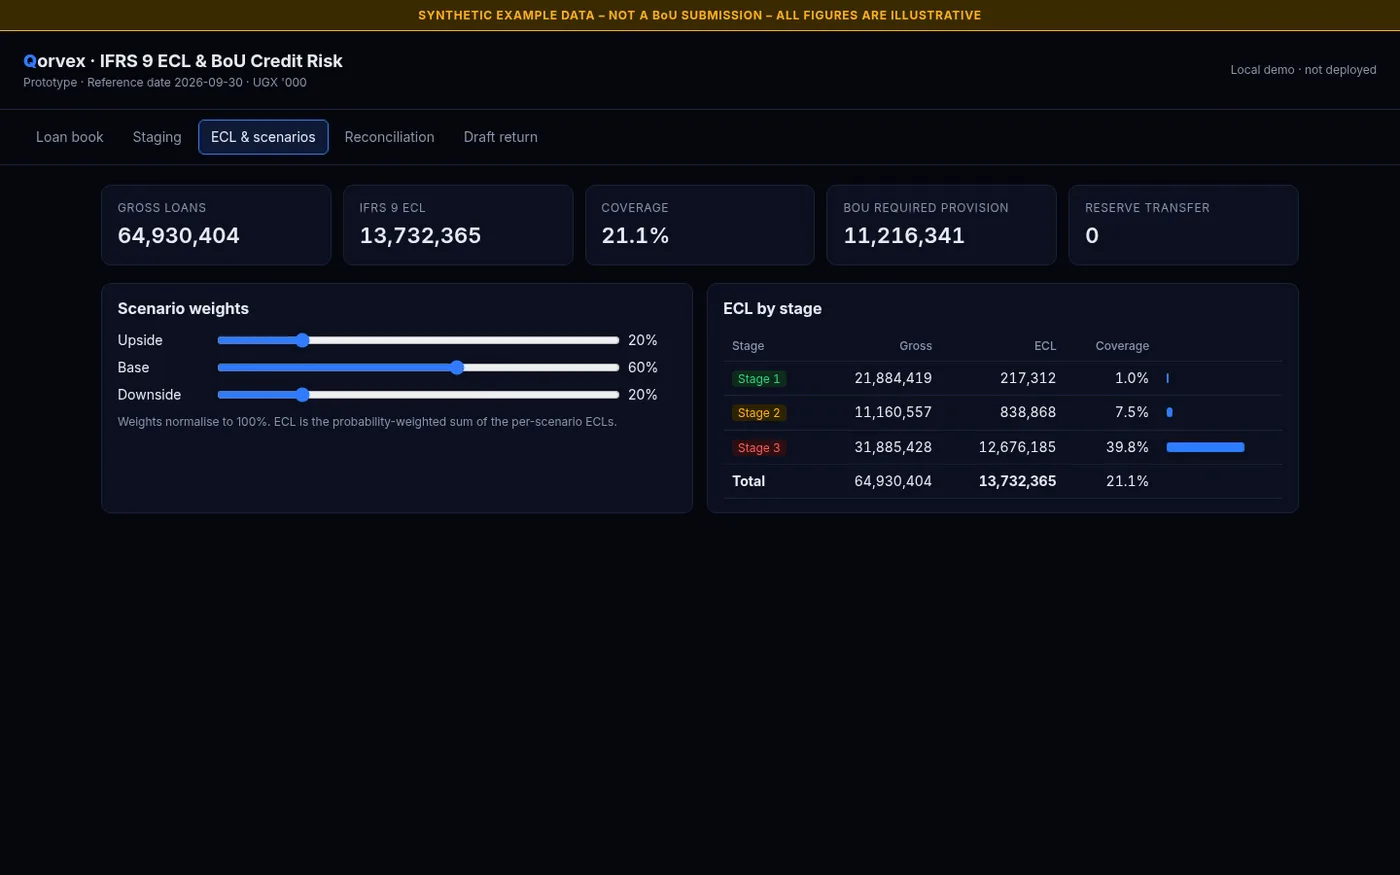
Industry
Banking
Focus
Credit risk
Expected credit loss from a loan book
Loans are staged under IFRS 9, losses are estimated and a draft monthly return layout is prepared.
01
The challenge
- —Staging and loss estimates live in fragile spreadsheets.
- —Assumptions are hard to trace from month to month.
- —Return preparation repeats the same manual steps.
02
What the system does
- —Stages each loan using configurable criteria.
- —Calculates expected losses with visible assumptions.
- —Lays out a draft return for review.
03
What the team sees
- —Stage movements and the reasons for them.
- —Loss estimates broken down by segment.
- —A reconciliation back to the loan book.
04
Next steps
- —Review the demo on its synthetic loan book.
- —Agree your staging rules and model inputs.
- —Validate outputs against a past period with your risk team.
Based on the IFRS 9 Credit Loss and BoU Return demo.
This is an illustrative example built on synthetic data. It does not describe a real client, and no results are claimed.